TL;DR
Paying extra toward student loans gives you a certain reduction in future interest. Investing gives you the potential for higher long-term growth, but with market risk. Lower-rate loans often make investing more attractive on paper, while high-rate loans usually deserve faster repayment. The right plan depends on your rate, loan type, cash reserves, employer match and ability to stay consistent.
Student Loan Payoff vs. Investing: What the Net Worth Math Actually Says
Why This Decision Is More Personal Than Most Advisors Admit
You receive a raise, clear a major monthly bill or finally build some breathing room in your budget. Now you have an extra $500 each month. Should it go toward student loans or investments?
Personal finance advice often treats this as a simple contest. One side says debt must disappear before investing. The other says low-rate debt is fine when investments could grow faster.
Both arguments can be reasonable. Neither works for every borrower.
A person with a 3.5% federal student loan, a stable emergency fund and a long investment horizon faces a different decision from someone carrying a 10.5% private student loan with little cash saved. A borrower working toward a federal forgiveness path should also review program rules before making aggressive extra payments, since paying down a balance early may work against that plan.
The goal is not to select the most impressive strategy. It is to choose the one that improves your financial position without exposing you to a risk you cannot manage.
The Core Mathematical Framework
Student loan payoff creates a predictable benefit: every extra payment reduces future interest charged on the balance, after outstanding interest and required amounts are handled according to the loan terms. Federal Student Aid states that federal student loans can be prepaid at any time without penalty.
Investing creates an uncertain benefit. Your account may grow over a long period, but market investments can lose value, sometimes for years. Investor.gov warns that market-risk investments cannot offer guaranteed profits.
That leaves one central comparison:
Loan interest rate avoided vs. investment return reasonably expected over your time horizon
If a loan costs 4% annually and you invest for decades, investing may produce the stronger long-term outcome. If a loan costs 10% or more, eliminating that debt becomes very difficult for a risky investment strategy to beat reliably.
Tax treatment, federal repayment protections, employer contributions and your stress level all affect the final choice. The interest rate gives you the starting point, not the complete answer.
The Break-Even Interest Rate
Broad U.S. stock market investments have produced strong long-term historical returns, and financial planning examples often use an assumed 7% annual return after accounting broadly for inflation. That figure is useful for illustration, but it is not a promise. Future returns could be higher, lower or negative during the years you need the money.
A loan rate is different. A fixed 7% student loan costs 7% according to its terms. Eliminating that balance reduces a known expense. Investing instead requires accepting uncertainty in pursuit of a higher result.
A practical framework looks like this:
- Loan rates around 4% or below: Long-term investing becomes more attractive mathematically, provided you have emergency savings and can tolerate market losses.
- Loan rates near 6% to 7%: The decision is close enough that stability, loan type and personal comfort may matter more than a spreadsheet projection.
- Loan rates above 8% to 10%: Aggressive repayment often becomes the stronger priority because the interest avoided is high and certain.
These are decision ranges, not rigid rules. Someone without emergency savings should rarely invest every extra dollar while remaining vulnerable to new debt from one unexpected bill.
Scenario A: A 4% Loan Rate Favors Long-Term Investing
Assume you have a manageable federal student loan at 4% and already cover the required payment. You also have $500 per month available for either extra payoff or investing.
Investing $500 monthly for 20 years at a hypothetical 7% annual return, compounded monthly, would grow to approximately $260,463. The total contributed would be $120,000, with the remaining amount coming from hypothetical growth.
That result is not guaranteed. Market performance will vary. But a 20-year time horizon gives investing time to recover from downturns and compound future gains.
Now consider a $20,000 student loan at 4% on a 10-year repayment schedule. The normal monthly payment is about $202. Paying an additional $500 each month would clear the loan in roughly 30 months instead of 120 months and save about $3,250 in interest.
Paying the loan early still improves your position. It removes debt quickly and frees your required monthly payment much sooner. But at a low interest rate and over a long investment horizon, the potential investment growth is much larger than the interest savings alone.
A fair comparison also requires one more step: after the loan is gone, the borrower using the payoff strategy could begin investing the freed payment. The better route depends on how consistently the person follows through after the balance reaches zero.
Scenario B: A 7% Loan Rate Creates a Close Call
At a 7% loan rate, the decision becomes less clear.
Paying extra toward a fixed 7% balance gives you a certain reduction in interest cost. Investing with an assumed 7% annual return gives you only a projection. Your portfolio might average more than 7% over time, but it might also perform far worse during a difficult stretch.
This is where risk tolerance matters. A borrower who sleeps poorly while carrying debt may gain more practical value from repayment than an investment projection suggests. Another borrower with a steady income, substantial cash reserves and a long horizon may accept market risk and continue investing.
Loan type matters here too. Federal student loans may carry repayment options and borrower protections that private loans do not offer in the same way. Giving up flexibility by aggressively paying federal debt may be less appealing than eliminating a private loan with limited protections.
At 7%, neither route is automatically foolish. The mistake is failing to choose a deliberate plan.
Scenario C: A 10% or Higher Loan Rate Usually Favors Payoff
High-rate private student loans change the equation sharply.
A 10% interest rate creates a known, expensive drag on your balance sheet. Paying that loan down reduces future interest without requiring a favorable stock market. To justify investing instead, you would need returns high enough to exceed the loan cost after investment risk and any applicable taxes.
That is a demanding hurdle.
For borrowers with student loans at 10% or above, it usually makes sense to secure any available workplace retirement match, maintain an emergency cash buffer and then direct additional money toward the expensive loan. A 10% balance can consume years of investment progress when left untreated.
Payoff also improves monthly cash flow once the debt is gone. That freed payment can then be redirected into retirement accounts or other long-term assets.
The Psychological Factor Nobody Can Put in a Formula
Math can estimate interest charges and projected investment balances. It cannot fully measure the burden of debt.
Some borrowers feel little emotional pressure from a low-rate student loan and are comfortable investing while making regular payments. Others find that debt affects career choices, housing decisions, family plans or day-to-day peace of mind.
That mental weight has a financial effect. Someone who clears a loan and then confidently invests each month may build more wealth than someone who chooses the mathematically stronger path but constantly pauses investing, changes strategies or spends the extra money.
There is no prize for following the spreadsheet while ignoring your own behavior. The best plan is the one you can continue during market declines, job changes and ordinary life expenses.
The Hybrid Strategy Is Often the Most Practical
Choosing between repayment and investing does not have to be all-or-nothing.
Start by building an emergency fund that protects you from relying on credit cards when something goes wrong. A three-month reserve of essential expenses is a useful initial target, followed by a larger cushion as your budget allows.
Next, capture any employer retirement match available through your workplace plan. The IRS explains that an employer may match employee contributions when the plan allows it. For example, a plan might contribute 50 cents for every dollar an employee contributes up to a stated limit. Missing an available match means passing up compensation offered through the plan, subject to its rules and vesting terms.
After that, divide extra money according to your loan rate and comfort level. Someone with a 6.5% loan might put $300 of a $500 monthly surplus toward debt and $200 into a Roth IRA, when eligible, or another investment account. Someone with a 3.5% federal loan may invest most of the extra money while making a smaller additional principal payment.
This approach builds assets while still reducing liabilities. It also prevents the feeling that progress depends entirely on one uncertain outcome.
Seeing Your Net Worth Impact
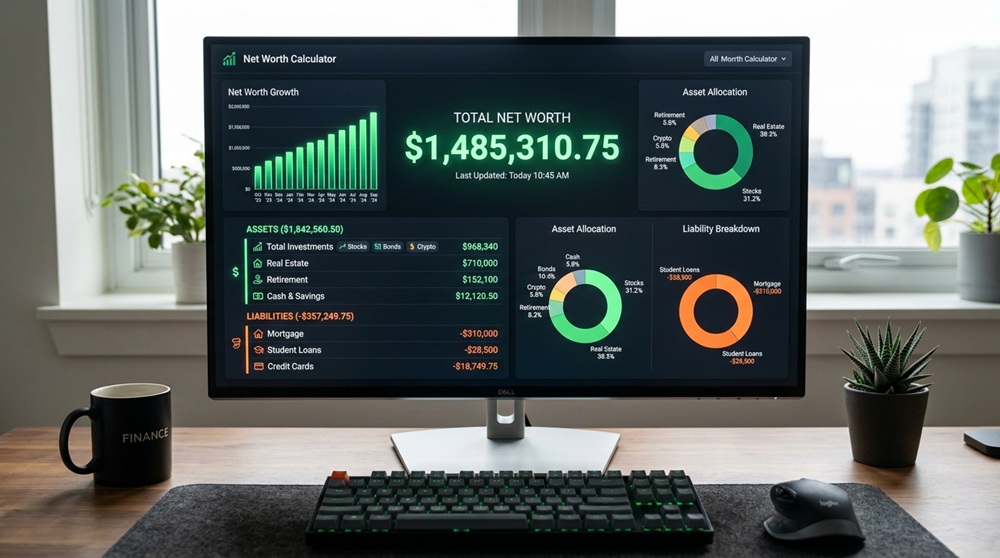
Before choosing a strategy, list your current assets and your complete student loan balance. Your net worth is the number that shows the combined result of paying debt and building investments.
Suppose you have $35,000 in retirement savings and $28,000 in student loans. Your net worth from those two categories is $7,000. If you pay $5,000 of loan principal using new income, your net worth rises to $12,000. If you invest $5,000 and the investment value holds, your net worth also rises to $12,000. The difference develops later through interest avoided on the loan and gains or losses on the investment.
Use a tool to calculate your net worth with all student loan balances included, then update the figure monthly as your plan continues. A falling loan balance, a growing investment account or both should eventually show up in the same total.
The trend matters more than one month’s result. Markets can fall even when investing is sensible, and an extra loan payment may feel modest before accumulated interest savings become visible.
Readers looking for more practical guidance on tracking assets, debts and financial progress can find additional resources at NetlyWorth.
Your Rate Guides the Strategy, Your Behavior Drives the Result
Low-rate student debt can leave room for long-term investing. Mid-range rates require a closer decision based on risk, loan protections and personal comfort. High-rate student debt often deserves urgent repayment after emergency savings and any available employer match are addressed.
Run your own numbers, choose a plan you can follow and measure the outcome through your net worth. The winning strategy is not the one that sounds best in theory. It is the one that steadily converts your income into a stronger balance sheet.